Top Pro Roofing SD is a referral marketplace. We connect San Diego County homeowners with CSLB-licensed C-39 roofers. We do not file claims, adjust losses, or predict your premium. Call (760) 750-5557.
File only after you have a written cause-and-scope estimate and you have read your deductible, roof-age terms, and recent claim history. A phone call to the carrier can open a CLUE entry even if you later wish you had paid a small repair yourself. This page is a homeowner checklist, not insurance advice.
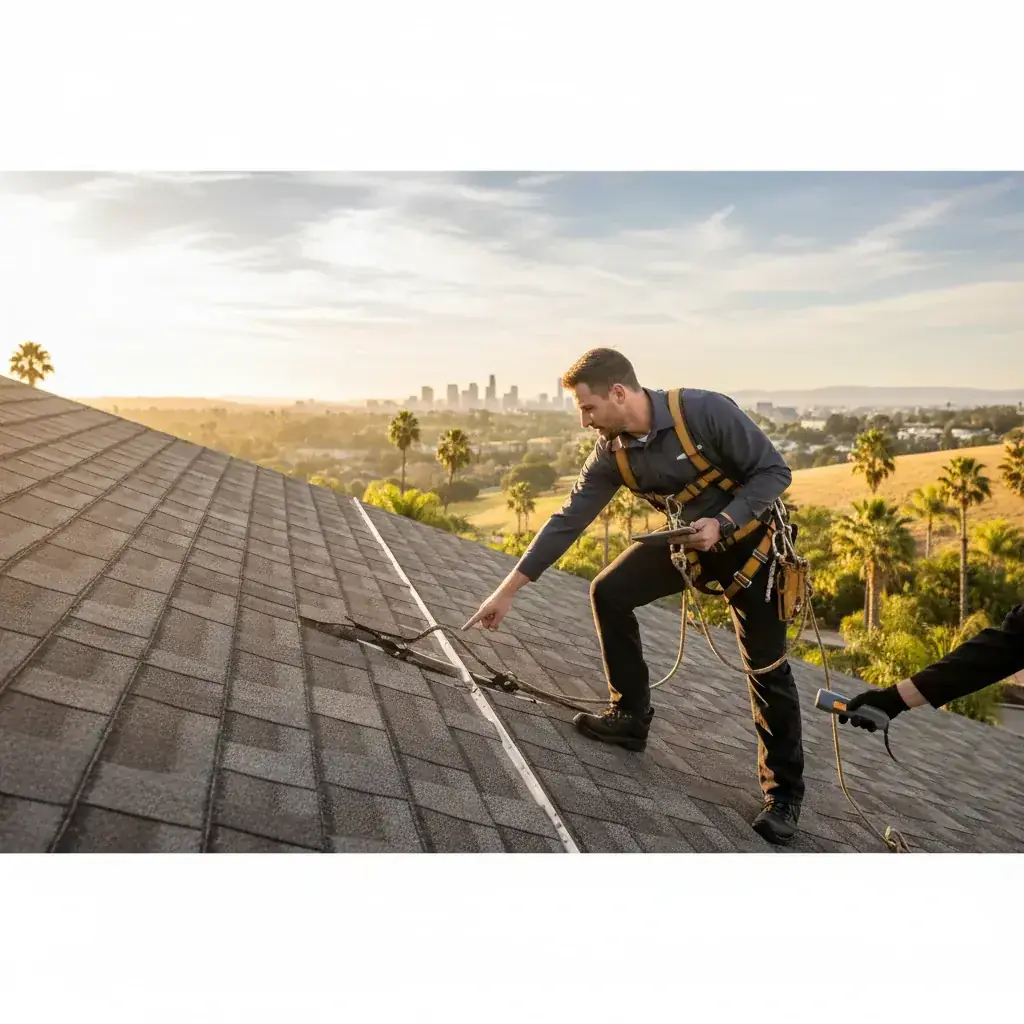
Get the estimate before the claim number
A useful pre-file visit produces photos, a line-item repair or replacement scope, and a plain statement of likely cause: a dated storm or impact versus long wear. The matched roofer works for you on that inspection. They do not work for the carrier.
We will not invent a 1.5x or 3x deductible rule, a 2026 California premium-hike percent, or a net-payout table. Those numbers depend on your policy, your carrier, and how underwriting treats this loss. Compare:
- Estimated work minus the deductible that actually applies (some policies split wind or named-storm deductibles as a percent of dwelling limit)
- Whether the roof is replacement cost or actual cash value
- Whether you can pay the repair without opening a claim file
If the estimate is close to the deductible, many homeowners pay out of pocket and keep the paper trail. If the scope is a full replacement after a documented event and the policy still pays replacement cost, filing is often the conversation worth having with the carrier and, if needed, the California Department of Insurance.
Four gates that change the decision
1. Deductible and peril
Read the declarations page. A non-wind deductible and a wind or wildfire percentage deductible are not the same check. A Santa Ana event and a slow leak from a 25-year shingle are not the same peril. Does homeowners insurance cover roof leaks in California and roof storm damage insurance claim split those paths.
2. CLUE before you file
CLUE (Comprehensive Loss Underwriting Exchange) is the loss history other carriers can see. Pull your own report at LexisNexis Consumer Disclosure. Claims commonly remain visible for years. A second or third recent claim is often harder on renewal shopping than the first. Withdrawing a claim can still leave a closed-without-payment mark. Ask the carrier how they report, in writing.
3. Roof age and ACV
Many California policies tighten roof coverage as the covering ages: actual cash value instead of replacement cost, or wind and hail limits. Filing a large claim on a roof already near an age cliff can also trigger a non-renewal conversation. Details: roof age and California insurance non-renewal and does insurance cover full roof replacement in California. We will not invent year cutoffs as if every admitted carrier used the same table.
4. Where you would land after a non-renewal
Several admitted carriers have restricted new California homeowner business in recent years. Confirm your zip and carrier with your agent. The California FAIR Plan is the residual market when the private market will not write you. It is a different product and a different price. Do not treat a blog multiplier as your quote.
When filing is usually a poor fit
Wear, age, and neglect. Sudden accidental damage is the usual covered story. Gradual granule loss, a 24-year roof that finally leaked, and skipped maintenance are typical exclusions. A denial can still appear on loss history.
Cosmetic-only marks. Isolated scuffs, light granule wash, or one cracked tile with no leak path often get denied. The attempt can still be a claim file.
You already have recent claims and this repair is small. The inspection still matters. Paying a ridge-cap repair yourself can be cheaper than another underwriting event. We will not price that repair here.
You cannot document a date of loss. If you skip filing but the damage is real, still get a dated written report and photos. A later claim without an incident date is easier to call wear.
When filing is usually worth the call
A dated storm, wind, hail, or fallen-tree event with visible damage and a scope well above the applicable deductible, especially with interior water into drywall or insulation.
Third-party impact (neighbor’s tree, vehicle) where your policy may pay first and subrogate. Document the other party. Do not guess liability.
You need the carrier’s process for a full replacement and the policy language still supports it. Follow roof insurance claim in California: step by step. Deadlines: roof insurance claim deadline in California. Policies often require prompt notice. Read your policy and current California claim-deadline guidance with counsel. This page is not a filing clock.
If a clearly covered, well-documented loss is delayed or lowballed, talk to a California insurance attorney. This page is not a bad-faith opinion. A weak or excluded loss still gets denied. A public adjuster is a separate licensed role: public adjuster for roof claims in California.
What to ask the roofer in writing
- Cause of loss in one sentence, with the date or weather they are tying it to
- Repair versus full replacement, and why
- What they photographed
- What they did not open (attic, drywall) and still consider unknown
- Whether they will attend an adjuster meeting if you file
Verify the C-39 at CSLB license check. Top Pro Roofing SD refers. The contractor’s contract, insurance, and warranty are theirs.
The Insurance Information Institute explains that a claim can affect future premiums. It does not set your California renewal. Ask your carrier for the surcharge or non-renewal rules that apply to your policy.
FAQ
Will one roof claim drop me? Often not by itself. Carrier, claim size, roof age, and prior CLUE rows all matter. Two recent claims is a common hard look. Nobody here can promise a renewal.
Does a small claim hurt as much as a large one? Underwriting often prices the fact of a loss, not only the dollars. That is why tiny claims are a poor default.
How long does CLUE keep a claim? Ask LexisNexis and your carrier. Plan on years, not months.
Should I wait or file fast? If you will file, notice the carrier promptly and keep the roofer’s dated report. If you might not file, still document. Then decide with the policy in hand.
Related California roof insurance reading
- Roof insurance claim in California: step-by-step process
- Does homeowners insurance cover roof leaks in California?
- Does insurance cover full roof replacement in California?
- Roof insurance claim deadline in California
- Public adjuster for roof claims in California
- Roof age and California insurance non-renewal
- Roof storm damage insurance claim
External resources
- Insurance Information Institute: How much does a claim raise my premium
- California Department of Insurance: Residential Insurance
- LexisNexis CLUE Consumer Disclosure
- California FAIR Plan
- CSLB License Check
When to call us
Before you open a claim, get a written roof estimate. Call (760) 750-5557 and we’ll connect you with a licensed local roofer for roof repair or roof replacement documentation. We do not tell the carrier you filed.